Settlement Hours Evolving Toward More Continuous Market

0
Settlement Hours Evolving Toward More Continuous Market

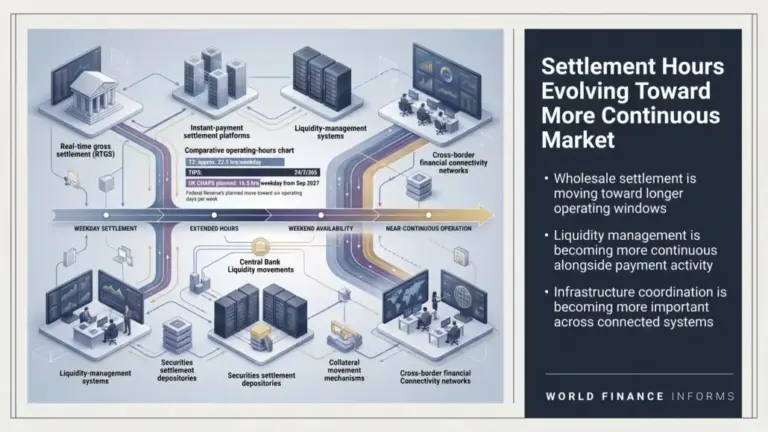
Settlement hours are becoming a more important part of financial-market infrastructure as payments, trading activity and liquidity management extend beyond traditional business-day boundaries.

The broader implication for financial markets is not simply whether settlement systems should remain open for longer, but how wholesale infrastructure can adapt to a financial system operating across increasingly extended or continuous periods. As instant-payment services already operate around the clock, greater demands are also being placed on the liquidity mechanisms and supporting infrastructure that enable these payment flows.

Financial Activity Extending Beyond Traditional Operating Windows

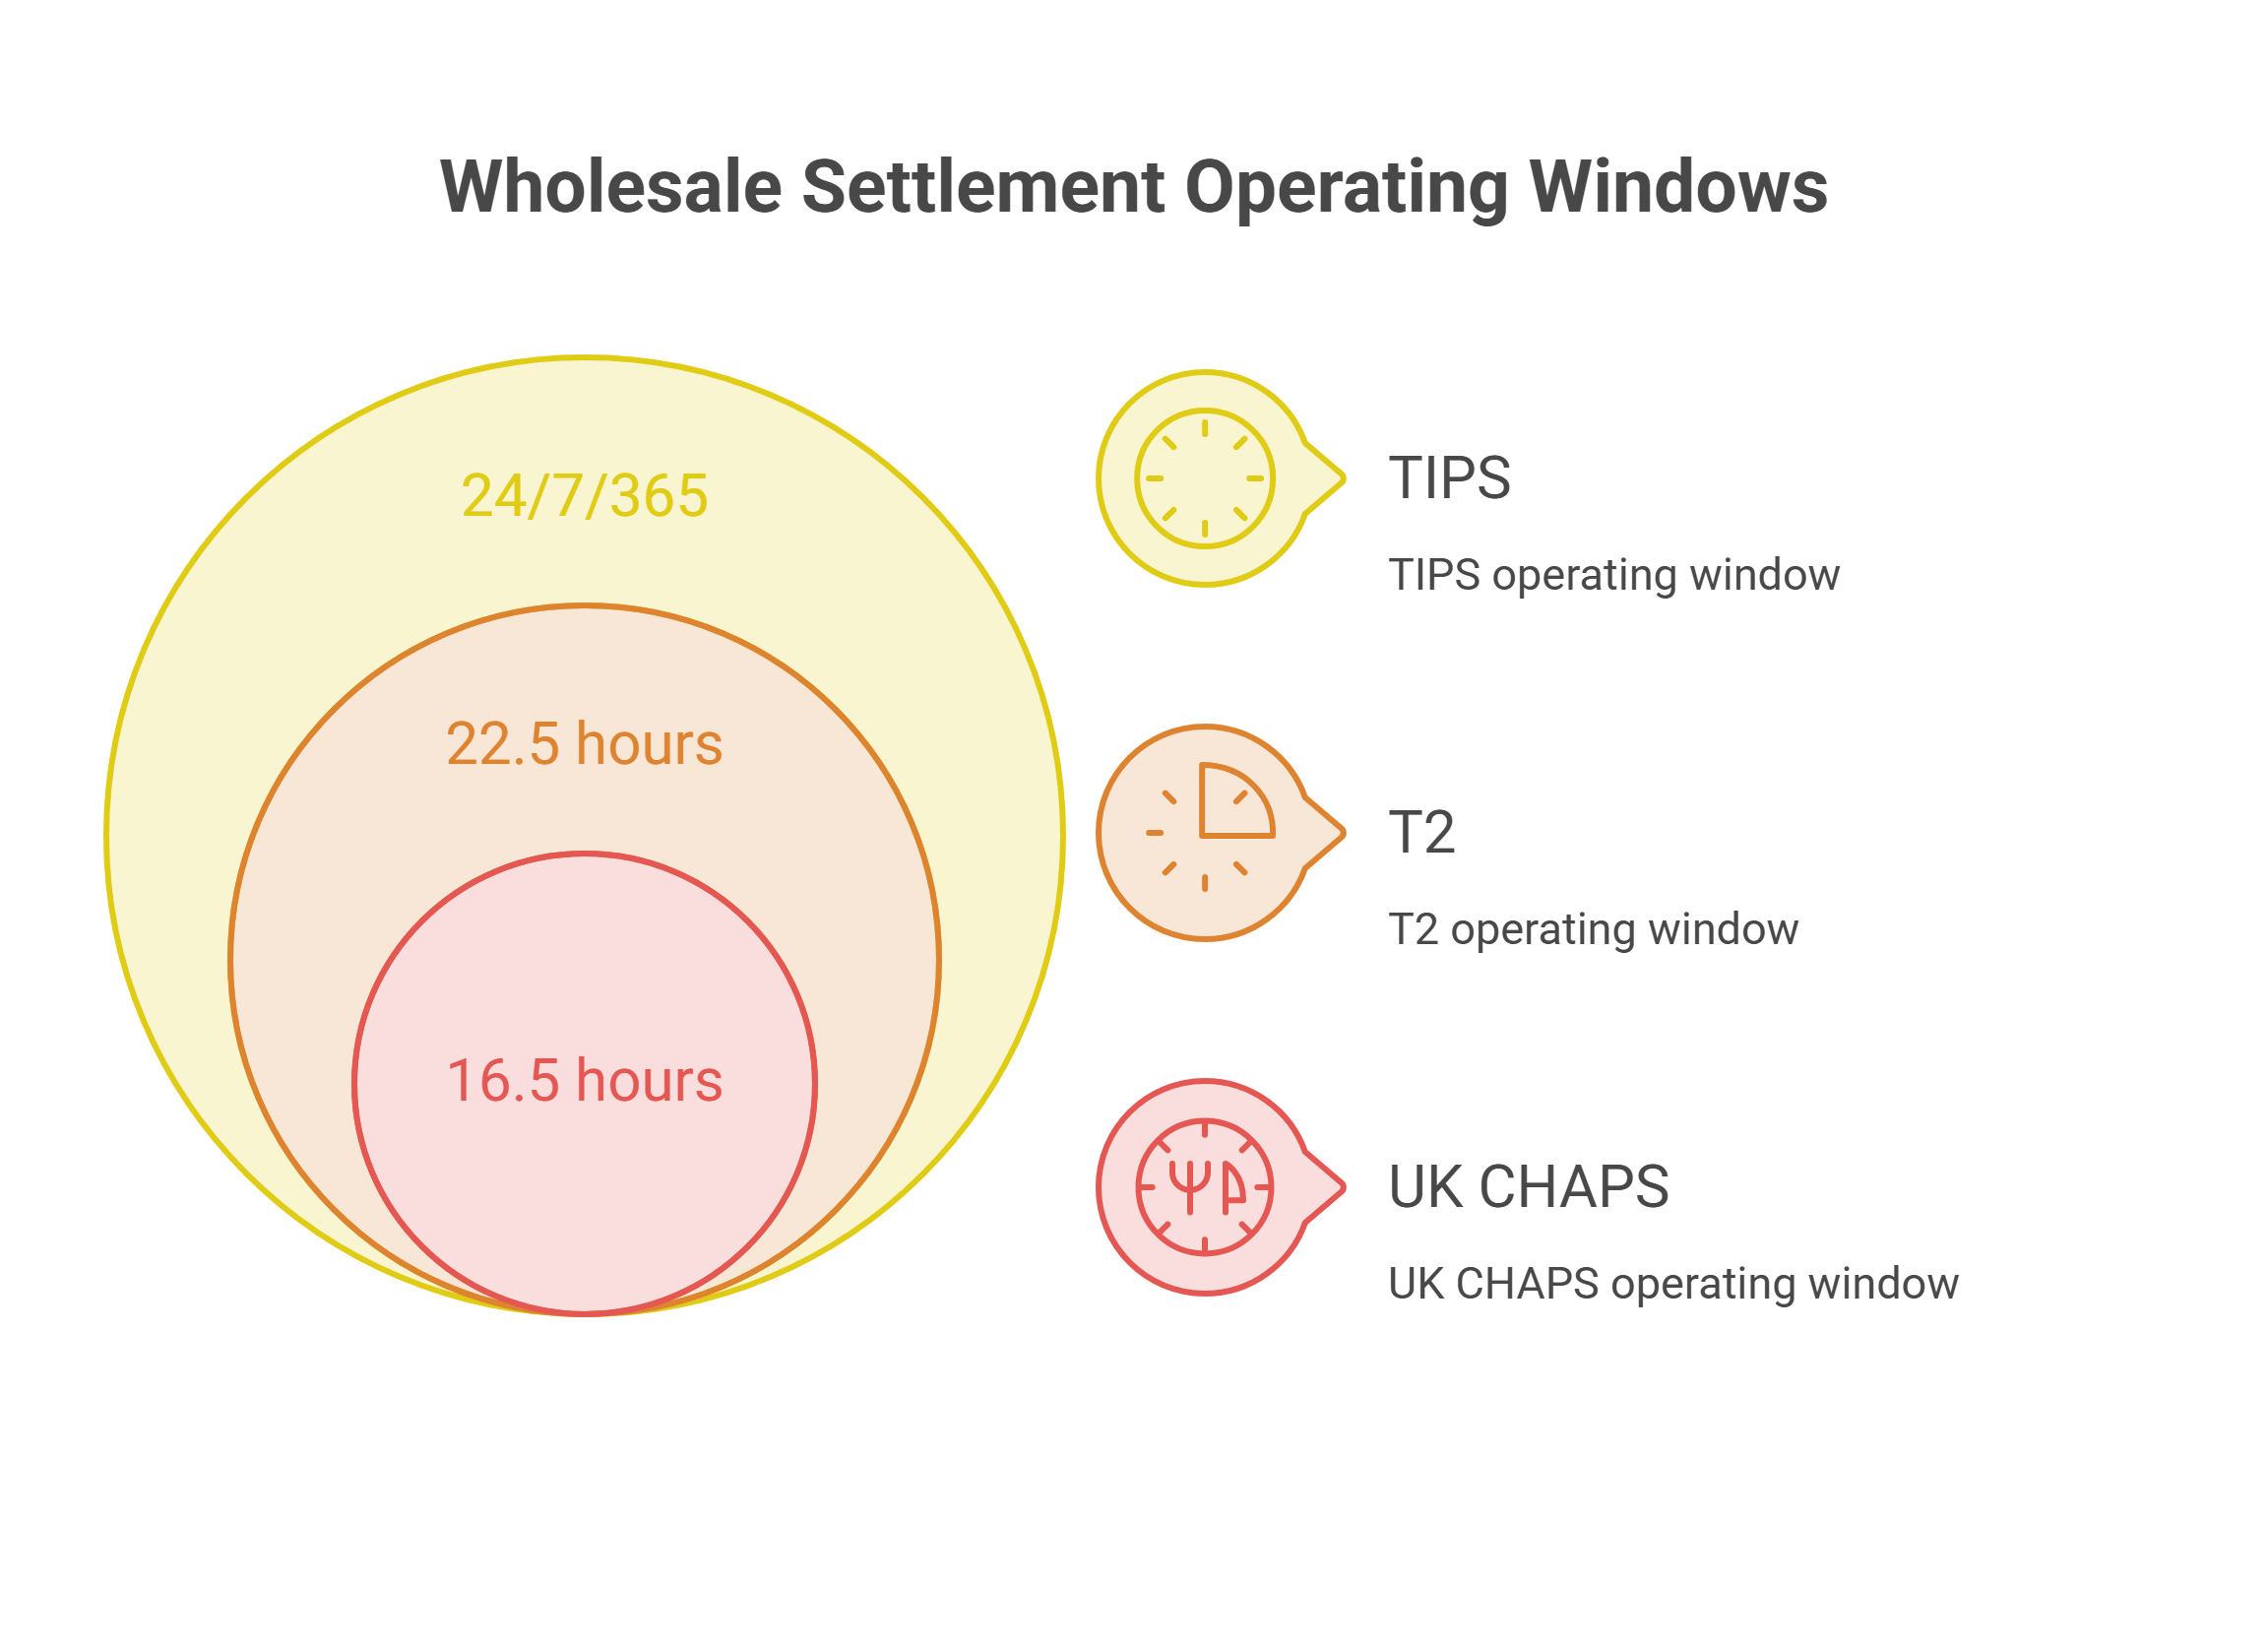
The pressure is particularly visible in wholesale payment infrastructure. The Eurosystem’s T2 system currently operates for around 22.5 hours on weekdays, while TIPS provides instant-payment settlement continuously. The ECB’s 2026 roadmap for extending T2 operating hours followed consultation with 125 entities across 19 countries and identified liquidity management for instant payments as the main motivation for extending operating availability. This suggests that the question around settlement hours is increasingly connected to how efficiently liquidity can move when payment activity continues outside conventional wholesale operating windows.

The European approach is developing gradually rather than moving immediately toward full 24/7 wholesale settlement. The ECB introduced measures in 2026 that include automated liquidity management and a short weekend T2 settlement window, while its longer-term roadmap considers near-continuous liquidity management and longer real-time gross settlement availability. The objective is to bring settlement infrastructure closer to the operating patterns already established in faster payment systems without creating unnecessary disruption to existing market processes.

Longer Settlement Availability Requiring Infrastructure Changes

Other major markets are considering similar changes. The Bank of England is extending CHAPS operating hours from 2027 and consulting on longer-term models that could include weekend settlement, while the Federal Reserve plans to expand Fedwire and the National Settlement Service to six operating days a week. These developments show that settlement hours are evolving across multiple financial systems, although the proposed models differ in scope, timing and operating structure.

The challenge is that longer availability affects more than transaction processing. Extending the settlement day can reduce the time available for maintenance, reconciliation and system recovery while creating new requirements around liquidity positioning, value dates and coordination between interconnected infrastructures. As settlement hours expand, market participants therefore need to consider not only when transactions can settle, but how cash, collateral and supporting systems remain available throughout the wider operating period.

Longer operating windows are changing how settlement infrastructure manages liquidity, maintenance and coordination across connected systems. The ECB’s phased approach recognises that extending wholesale availability requires supporting mechanisms rather than simply keeping existing services open for more hours. Automated liquidity transfers, weekend settlement capacity and later cut-offs can help participants manage funding positions when payment activity continues beyond conventional wholesale windows. The Bank of England is pursuing a similar direction, with an early-morning CHAPS extension planned from September 2027 and consultation on longer-term models that could include weekend availability.

Liquidity Management Becoming More Continuous

The main operational issue is liquidity. When instant-payment systems remain available around the clock, banks need ways to reposition central-bank liquidity outside traditional wholesale windows. The ECB has introduced automated liquidity-management measures for TIPS and a short weekend T2 settlement window, while its longer-term roadmap considers near-continuous central liquidity management. These changes indicate that settlement hours are increasingly part of the liquidity architecture rather than simply a calendar setting.

A longer operating day also creates new demands on value dating, reconciliation and maintenance. Firms need clear boundaries for accounting and interest calculations even when transactions extend later into the day or across weekends. Maintenance and recovery periods can become harder to schedule where payment, securities and collateral systems depend on one another.

Infrastructure Coordination Becoming More Important

Europe, the UK and the United States are taking different approaches to extending settlement hours. T2 is moving through a phased roadmap, CHAPS is extending its opening time before considering broader models, and the Federal Reserve plans to add Sundays and weekday holidays to Fedwire and the National Settlement Service. The approaches differ, but all point toward closer alignment between wholesale settlement and more continuous financial activity.

This makes settlement hours an infrastructure-coordination issue as much as an operating-hours issue. Extending one service has limited value when another connected system remains unavailable. Synchronising payment, securities, collateral and liquidity systems will therefore become more important, particularly for cross-border activity. This creates a natural link to settlement infrastructure supporting continuously available markets.